Prestige Garden Breeze EMI calculator

Featured Image of Prestige Garden Breeze EMI calculator


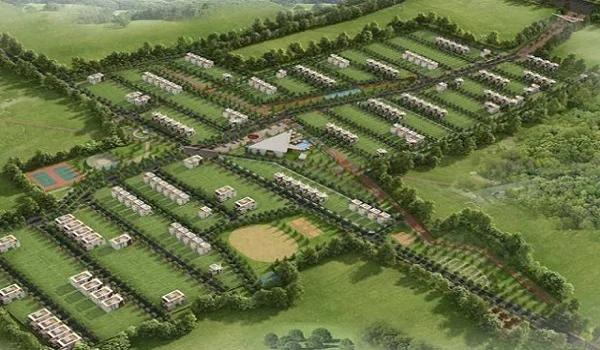
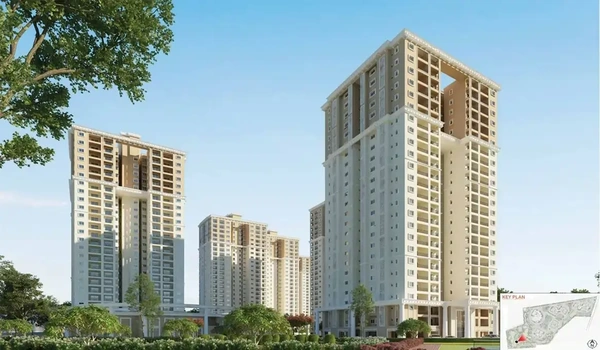
Prestige Garden Breeze EMI calculator helps you find your monthly loan payment, starting from ₹73,815 per month for a ₹96 Lakh loan on a 2 BHK home priced at ₹1.20 Crores with an 8.50% interest rate over 30 years. It works for all 655 homes in Phase 7 of The Prestige City, which covers 10 acres on Sarjapur Road in Bangalore under Karnataka RERA number PRM/KA/RERA/1251/308/PR/080926/008919. The tool factors in the standard 80% bank loan limit and the builder's 20:20:60 payment timeline, so you know your exact costs before possession on 30 December 2030.

The calculator focuses on the main cost of the flat and keeps extra charges, such as Karnataka stamp duty and GST, separate. It shows how much of your monthly payment goes toward interest and how much goes toward the loan amount. This makes it easier to plan your monthly budget and savings.

How the Prestige Garden Breeze EMI Calculator Works


The Prestige Garden Breeze EMI calculator uses the standard reducing balance math formula to work out your exact monthly payments for any loan tenure. Banks across India use this standard equation:

EMI = [ P × R × (1 + R)^N ] / [ (1 + R)^N - 1 ]

Three simple details decide your final monthly payment:

  • Loan Amount (P): The money you borrow from the bank after paying your 20% down payment on the flat.
  • Monthly Interest Rate (R): The yearly loan rate divided by 12 months (for example, 8.50% per year divided by 12 equals 0.007083).
  • Loan Time (N): The total number of months you take to pay back the loan, from 120 months (10 years) up to 360 months (30 years).

In the first few years of your loan, most of your monthly EMI pays the interest, while later years pay off the actual loan amount much faster.

Apartment Prices, Down Payments, and Home Loan Limits


Prestige Garden Breeze offers home sizes from 1,080 sq ft to 3,069 sq ft, each with clear down payment rules and loan limits. Most major banks will fund up to 80% of the agreement value of your flat.

Apartment Type Super Built-up Area (Sq Ft) Starting Price (₹) Minimum 20% Down Payment (₹) Maximum 80% Home Loan (₹)
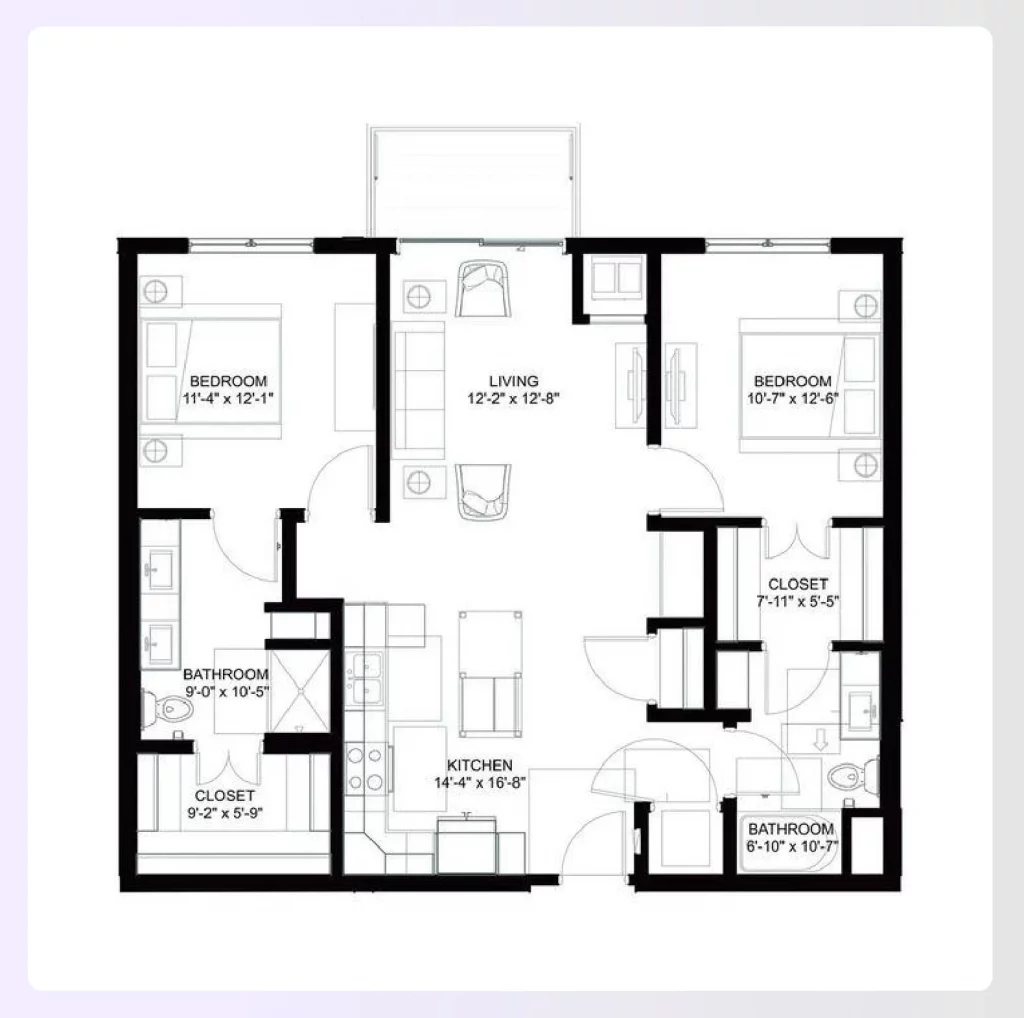
2 BHK (2T) 1,080 – 1,140 ₹1.20 Cr* onwards ₹24,00,000 ₹96,00,000
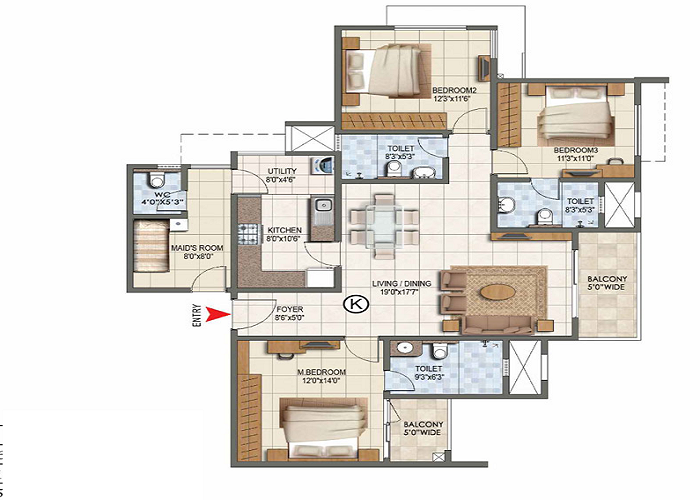
3 BHK (2T) 1,470 – 1,570 ₹1.62 Cr* onwards ₹32,40,000 ₹1,29,60,000
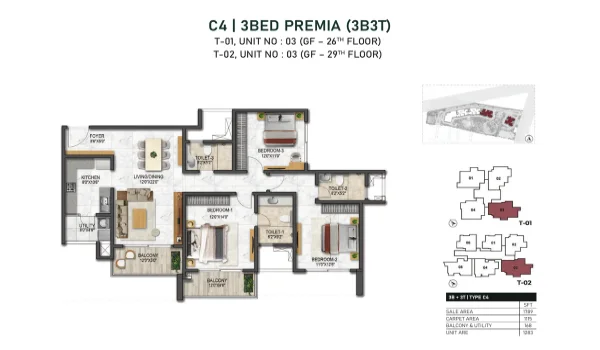
3 BHK (3T) 1,720 – 1,790 ₹1.89 Cr* onwards ₹37,80,000 ₹1,51,20,000
4 BHK Penthouse 2,779 – 3,069 ₹3.56 Cr* onwards ₹71,20,000 ₹2,84,80,000

Monthly EMI Breakdown for 2, 3, and 4 BHK Units


Your monthly loan payment changes with the loan tenure you pick, based on an 80% loan at an 8.50% yearly interest rate. A longer loan term brings down your monthly EMI, but you end up paying more total interest to the bank over time.

2 BHK Apartment (80% Loan Amount: ₹96 Lakhs)

Borrowing ₹96,00,000 for a ₹1.20 Crore 2 BHK home means an EMI of ₹83,346 per month for 20 years, with total interest of ₹1,04,03,040.

  • 10 Years (120 Months): ₹1,19,091 per month | Total Interest: ₹46,90,920
  • 15 Years (180 Months): ₹94,534 per month | Total Interest: ₹74,16,120
  • 20 Years (240 Months): ₹83,346 per month | Total Interest: ₹1,04,03,040
  • 30 Years (360 Months): ₹73,815 per month | Total Interest: ₹1,69,73,400

3 BHK (2T) Apartment (80% Loan Amount: ₹1.296 Crores)

A loan of ₹1,29,60,000 for a ₹1.62 Crore flat requires an EMI of ₹1,12,517 per month for 20 years, with total repayments reaching ₹2,70,04,080.

  • 10 Years (120 Months): ₹1,60,773 per month | Total Interest: ₹63,32,760
  • 15 Years (180 Months): ₹1,27,621 per month | Total Interest: ₹1,00,11,780
  • 20 Years (240 Months): ₹1,12,517 per month | Total Interest: ₹1,40,44,080
  • 30 Years (360 Months): ₹99,650 per month | Total Interest: ₹2,29,14,000

3 BHK (3T) Apartment (80% Loan Amount: ₹1.512 Crores)

Financing ₹1,51,20,000 on a ₹1.89 Crore home sets your monthly EMI at ₹1,31,270 over a 20-year term.

  • 10 Years (120 Months): ₹1,87,569 per month | Total Interest: ₹73,88,280
  • 15 Years (180 Months): ₹1,48,891 per month | Total Interest: ₹1,16,80,380
  • 20 Years (240 Months): ₹1,31,270 per month | Total Interest: ₹1,63,84,800
  • 30 Years (360 Months): ₹1,16,259 per month | Total Interest: ₹2,67,33,240

4 BHK Penthouse (80% Loan Amount: ₹2.848 Crores)

A penthouse loan of ₹2,84,80,000 has a monthly EMI of ₹2,47,250 over 20 years, which drops to ₹2,18,970 over 30 years.

  • 10 Years (120 Months): ₹3,53,300 per month | Total Interest: ₹1,39,16,000
  • 15 Years (180 Months): ₹2,80,441 per month | Total Interest: ₹2,19,99,380
  • 20 Years (240 Months): ₹2,47,250 per month | Total Interest: ₹3,08,60,000
  • 30 Years (360 Months): ₹2,18,970 per month | Total Interest: ₹5,03,49,200
Aligning the EMI Calculator with the 20:20:60 Payment Plan


Prestige Garden Breeze follows a 20:20:60 construction payment plan with three clear payment stages. The booking amount is ₹15 lakh for a 2 BHK and ₹20 lakh for a 3 BHK. The plan links each payment to the progress of construction at the site.

  • First 20% (Booking): You pay this within 90 days of booking from your own savings, which includes your initial deposit.
  • Second 20% (Ground Work): You pay this stage when the building work begins, and the basement is cast.
  • Final 60% (Tower Work to Possession): Your bank pays this money in parts as the tower floors get built, right up to key handover on 30 December 2030.

During construction, you can choose how to service your loan:

  • Pre-EMI Option: You pay only the monthly interest on the money released by the bank so far, keeping payments small during the build.
  • Full EMI Option: You start paying the full EMI right away, which helps clear your loan faster and cuts your total interest bill.

Tax Deductions on Your Monthly Home Loan EMI


Indian tax laws give you deductions on both the principal and interest of your home loan under the Old Tax Regime, which brings down your real out-of-pocket costs each year. These benefits come under two main parts of the tax law:

  • Section 80C (Principal Amount): You can claim tax deductions up to ₹1,50,000 each year on the principal you pay back, as long as you keep the home for at least 5 years.
  • Section 24(b) (Interest Amount): You can claim up to ₹2,00,000 every year on the loan interest you pay for a home you live in.
  • Joint Loan Benefit: If you take the loan jointly with a working spouse, both of you can claim these deductions, giving your family up to ₹3,00,000 off on principal and ₹4,00,000 off on interest every year.

These tax savings lower your true interest rate by around 1% to 1.5% each year, depending on your tax bracket.

How Interest Rates and Prepayments Lower Your Total Outgo


Even a small drop of 0.50% in your interest rate saves you several lakhs of rupees on a large home loan at Prestige Garden Breeze. You can easily cut down your total loan cost with two simple steps:

  • Credit Score Check: A credit score of 750 or higher gets you the lowest loan rates from top banks, while lower scores add extra margin fees.
  • Extra Yearly Payments: Paying just one extra EMI each year cuts a 20-year loan down by about 3 years.
  • Zero Prepayment Fees: Indian banking rules state that banks cannot charge extra fees when you make part-payments on floating-rate home loans.

FAQs


1. What is the minimum down payment for a 2 BHK at Prestige Garden Breeze?

The 20% down payment on a ₹1.20 Crore 2 BHK is ₹24,00,000, which includes your initial booking deposit of ₹15 Lakhs.

2. What is the monthly EMI for a 3 BHK home over 20 years?

For a 3 BHK (2T) unit priced at ₹1.62 Crores with an 80% loan of ₹1,29,60,000, the monthly EMI is ₹1,12,517 at an 8.50% interest rate over 20 years.

3. How does Pre-EMI differ from Full EMI during the building phase?

Pre-EMI covers only the interest on the money paid out by the bank as floors are built, while Full EMI pays both principal and interest from day one to clear your loan sooner.

4. Does this calculator show stamp duty and property registration charges?

No, the calculator shows payments only for the base flat loan, so you will need to pay Karnataka stamp duty and registration fees directly from your savings at the time of registration.

5. Can I make part-payments on my home loan without extra charges?

Yes, banks do not charge penalty fees when you pay extra money toward floating-rate home loans, letting you clear your loan balance whenever you have spare cash.

Enquiry
Enquire Now